Yes. Under Republic Act No. 9225, also known as the Citizenship Retention and Re-acquisition Act of 2003, natural-born Filipinos who reacquire or retain their Philippine citizenship hold the exact same constitutional freehold property rights as resident Filipino citizens. Dual citizens can purchase, register, and inherit unlimited private residential, commercial, industrial, and agricultural land throughout the Philippines without statutory area ceilings.
A widespread misconception across international expatriate groups suggests that dual citizens face a 1,000 square meter ceiling on residential land. That statutory restriction applies solely to former Filipino citizens who have not reacquired their Philippine citizenship under Republic Act 9225 and remain purely foreign passport holders under Batas Pambansa Blg. 185 and Republic Act No. 8179. Once you complete your dual citizenship oath and secure your Identification Certificate from the Bureau of Immigration or a Philippine Foreign Service Post, the 1,000 square meter limit vanishes entirely.
However, exercising freehold land rights as a dual citizen requires strict documentary compliance at both the Bureau of Internal Revenue (BIR) and the Registry of Deeds (RD). Presenting a foreign passport alone during a title transfer will prompt examiners to suspend registration under Section 10 of Presidential Decree No. 1529. As a licensed real estate appraiser and practitioner handling provincial conveyancing across Ilocos Sur and Northern Luzon, I have structured this definitive legal and operational guide to walk dual citizens through the statutory framework, mandatory Bureau of Immigration documentation, worked tax calculations, remote closing workflows, and fraud prevention protocols.
Planning a Land Purchase in the Philippines as a Dual Citizen?
Our licensed team conducts on-site due diligence, Registry of Deeds chain-of-title audits, and complete BIR ONETT conveyancing for dual citizens and overseas buyers in Ilocos Sur and Northern Luzon.
1. The Legal Foundation: Republic Act No. 9225 and Constitutional Land Rights
To understand why dual citizens can own private land without statutory restrictions, one must examine the interaction between the 1987 Philippine Constitution and Republic Act No. 9225.
Article XII, Section 7 of the 1987 Philippine Constitution
The fundamental charter of the Philippines establishes a strict nationalist policy regarding land ownership. Article XII, Section 7 of the 1987 Constitution states:
“Save in cases of hereditary succession, no private lands shall be transferred or conveyed except to individuals, corporations, or associations qualified to acquire or hold lands of the public domain.”
Section 2 and Section 3 of Article XII clarify that only citizens of the Philippines or corporations whose capital is at least 60 percent owned by Filipino citizens are qualified to acquire private lands. Non-Filipino foreign nationals are constitutionally barred from holding freehold title to Philippine land, regardless of how much capital they invest.
Section 5 of Republic Act No. 9225: The Restoration of Full Rights
Republic Act No. 9225, enacted on August 29, 2003, fundamentally reformed Philippine nationality law. Prior to RA 9225, under Commonwealth Act No. 63, a Filipino who became a naturalized citizen of another nation automatically lost Philippine citizenship. Consequently, they became foreign nationals subject to constitutional land ownership bans.
Republic Act No. 9225 changed this legal reality. Section 2 declares that natural-born citizens of the Philippines who have lost their Philippine citizenship by reason of their naturalization as citizens of a foreign country are deemed to have never lost their Philippine citizenship upon taking the oath of allegiance. Section 5 explicitly delineates the civil and property rights of individuals who reacquire or retain their Philippine nationality:
“Civil and Political Rights. Those who retain or reacquire Philippine citizenship under this Act shall enjoy full civil and political rights and be subject to all attendant liabilities and responsibilities under existing laws of the Philippines…”
Because property ownership is a core civil right under Philippine law, a natural-born Filipino who takes the oath of allegiance under RA 9225 is recognized as a full Philippine citizen. They are no longer treated as foreign nationals or former citizens. Consequently, they possess the unrestricted right to acquire, purchase, lease, mortgage, donate, or inherit private real property across the Philippine archipelago.
Natural-Born Citizenship as a Mandatory Precondition
It is vital to emphasize that Republic Act No. 9225 applies exclusively to natural-born citizens of the Philippines. Article IV, Section 2 of the 1987 Constitution defines natural-born citizens as:
- Individuals who are citizens of the Philippines from birth without having to perform any act to acquire or perfect their Philippine citizenship.
- Those who elect Philippine citizenship upon reaching the age of majority pursuant to the provisions of the 1935 Constitution.
If an individual became a Filipino citizen purely through judicial or administrative naturalization and subsequently acquired foreign citizenship, they are ineligible for dual citizenship under RA 9225. For natural-born Filipinos, however, dual citizenship restores absolute freehold capacity.
2. Comprehensive Comparison: Dual Citizens vs Former Citizens vs Foreign Nationals
Much of the confusion surrounding land acquisition in the Philippines stems from conflating three distinct legal classifications: dual citizens, former Filipino citizens, and foreign nationals. Each category operates under completely different legal regimes, area limits, and documentary thresholds.

| Legal Category | Governing Statute | Land Ownership Ceilings | Permitted Land Types | Mandatory Registration Documents |
|---|---|---|---|---|
| Dual Citizen | Republic Act No. 9225 (Citizenship Retention and Re-acquisition Act) | Unlimited (No statutory area restrictions whatsoever) | Residential, Commercial, Agricultural, Industrial, Raw Land | Bureau of Immigration Identification Certificate (IC), Order of Approval, Oath of Allegiance |
| Former Filipino Citizen (Residential Use) | Batas Pambansa Blg. 185 | Maximum 1,000 sq.m. (Urban) or 1 hectare / 10,000 sq.m. (Rural) | Residential land only (Strictly personal dwelling) | Sworn Affidavit of Landholding under BP 185, Birth Certificate, Foreign Passport |
| Former Filipino Citizen (Commercial / Business Use) | Republic Act No. 8179 (Foreign Investments Act Amendment) | Maximum 5,000 sq.m. (Urban) or 3 hectares / 30,000 sq.m. (Rural) | Commercial, Industrial, Agricultural, Tourism business use | Sworn Statement of Business Purpose, LGU Business Permit, SEC/DTI Registration |
| Purely Foreign National (Foreign Spouse / Investor) | 1987 Constitution Article XII, Section 7 | 0 sq.m. (Direct freehold ownership strictly prohibited) | Condominium units up to 40% foreign building quota; long-term lease | Passport, Alien Certificate of Registration (ACR I-Card), or 50-year registered lease contract |
Why the 1,000 Square Meter Limit Does Not Apply to Dual Citizens
Batas Pambansa Blg. 185 was enacted in 1982 to allow former natural-born Filipinos who had taken foreign citizenship to acquire a modest piece of land for their personal residential use upon retirement. BP 185 instituted strict caps: up to 1,000 square meters in urban areas or 10,000 square meters (1 hectare) in rural areas. Furthermore, a buyer under BP 185 cannot own both urban and rural residential parcels simultaneously, and if they already own urban land, they cannot acquire additional parcels if the total exceeds 1,000 square meters.
When Republic Act No. 9225 was enacted in 2003, it superseded these restrictions for anyone who actively reacquires Philippine citizenship. A dual citizen is legally a Filipino citizen. Therefore, they are not constrained by Batas Pambansa Blg. 185. A dual citizen can purchase a 200-square-meter residential lot in Metro Vigan, a 5-hectare agricultural farm in Magsingal, and a commercial building parcel in Candon City without violating any Philippine property statute.
Property Rights of Non-Filipino Foreign Spouses
A frequent scenario among overseas Filipinos involves a dual citizen married to a foreign national (such as an American, Canadian, Australian, or European citizen). How does the law treat the foreign spouse during property acquisition?
- Sole Registered Owner: The land must be registered exclusively in the name of the Filipino dual citizen spouse. Under established Supreme Court jurisprudence (Cheesman v. Intermediate Appellate Court, G.R. No. 74833), a foreign spouse cannot be listed as a co-owner of private land because of the constitutional prohibition.
- Deed of Absolute Sale Wording: The Deed of Absolute Sale and the resulting Transfer Certificate of Title (TCT) will read: “Juan Dela Cruz, Filipino, married to Jane Smith, American citizen”. The phrase “married to Jane Smith” is merely descriptive of the buyer’s marital status; it does not confer legal ownership or co-ownership of the land upon the foreign spouse.
- Death of the Dual Citizen Spouse: If the Filipino dual citizen passes away intestate, the foreign spouse can inherit a portion of the real estate through hereditary succession pursuant to the constitutional exception in Article XII, Section 7. However, the foreign spouse cannot sell or transfer that inherited land to another foreign national; any subsequent conveyance must be made to a qualified Filipino citizen or dual citizen.
3. Mandatory Documentation Docket for Registry of Deeds and BIR ONETT
While the law is unambiguous regarding dual citizen property rights, administrative compliance is where most overseas transactions face frustrating delays. When a property conveyance is submitted for registration, both the Bureau of Internal Revenue One-Time Transaction (BIR ONETT) unit and the local Registry of Deeds examine the buyer’s citizenship credentials with exceptional scrutiny.
If a buyer presents a foreign passport (such as a US, Canadian, or UK passport) on the Deed of Absolute Sale without supporting dual citizenship documentation, the Registry of Deeds will treat the transaction as a conveyance to a foreign national and issue a formal Notice of Denial or Suspension of Registration.
| Required Document | Issuing Authority | Purpose in Land Acquisition | Registry of Deeds and BIR Requirement |
|---|---|---|---|
| Identification Certificate (IC) | Bureau of Immigration (BI) or Philippine Foreign Service Post | Conclusive legal proof of reacquisition or retention of Philippine citizenship under RA 9225 | Certified True Copy or Original presented for verification; Registry of Deeds inspects security seals |
| Order of Approval | Bureau of Immigration Commissioner or Philippine Consul General | Administrative decree confirming the petition for dual citizenship was reviewed and granted | Required by BIR ONETT for electronic Certificate Authorizing Registration (eCAR) issuance |
| Sworn Oath of Allegiance | Bureau of Immigration or Philippine Embassy / Consulate | Official oath taken by the citizen swearing allegiance to the Republic of the Philippines | Mandatory attachment establishing the exact legal date citizenship was formally restored |
| Philippine Tax Identification Number (TIN) | Bureau of Internal Revenue (BIR Form 1904) | Mandatory tax identification number for all property buyers in the Philippines | Both buyer and seller must have valid TINs; required to process Capital Gains Tax and DST |
| Valid Government Identification | Philippine Government / Foreign Government | Identity verification conforming to the 2004 Rules on Notarial Practice | Philippine Passport, Dual Citizen IC, or Foreign Passport coupled with IC details |
| Special Power of Attorney (SPA) | Philippine Consulate or Foreign Notary with Hague Apostille | Required if the dual citizen is buying the property remotely through a representative | Must specify property details (TCT number, lot number, area) under Civil Code Article 1878 |
The Bureau of Immigration Identification Certificate (IC)
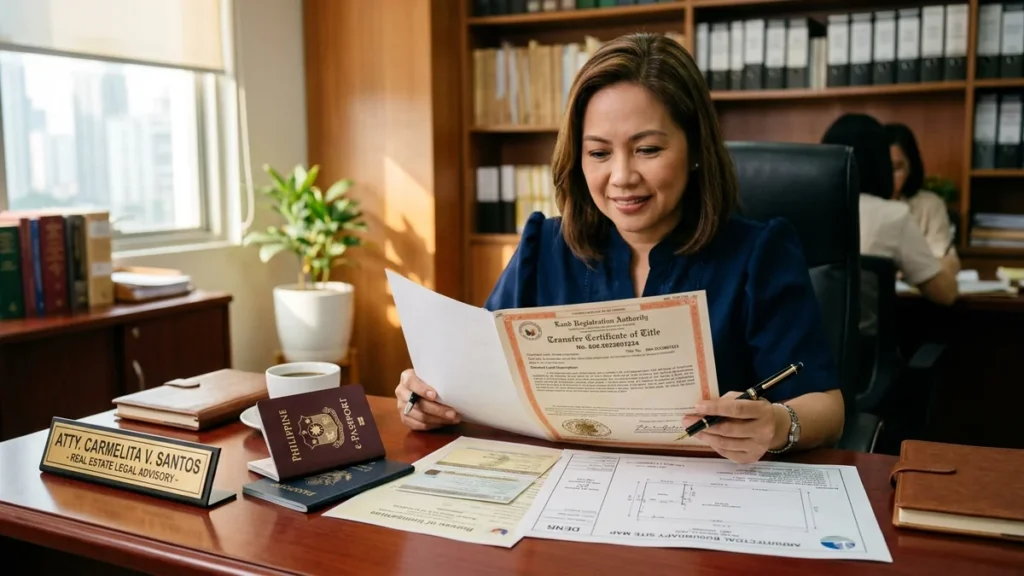
The Identification Certificate is the single most vital document for a dual citizen purchasing real estate. It features the official seal of the Republic of the Philippines, the dual citizen’s photograph, their Alien Certificate of Registration cancellation number (if applicable), and an express certification stating that the individual is recognized as a citizen of the Philippines pursuant to Republic Act No. 9225.
When drafting the Deed of Absolute Sale, the dual citizen’s citizenship should be stated as: “Filipino citizen under Republic Act No. 9225, as evidenced by Bureau of Immigration Identification Certificate No. [Number], issued on [Date] at [Location]”. Providing this specific statutory reference prevents the title examiner from questioning the buyer’s legal capacity.
The 5-Step Dual Citizenship Reacquisition Pipeline
For natural-born Filipinos residing abroad who have not yet formalized their dual citizenship status, the reacquisition process must precede any land closing. The administrative petition follows five distinct stages:
- Application Filing: Submit the verified petition for dual citizenship at the Philippine Embassy or Consulate holding jurisdiction over your foreign residence, or at the Bureau of Immigration Main Office in Intramuros, Manila, if currently visiting the Philippines. Required attachments include your PSA Birth Certificate, foreign naturalization certificate, foreign passport, and recent passport-style photographs.
- Evaluation and Clearance: Consular officers or immigration attorneys review your birth records to establish natural-born Philippine citizenship status under the Constitution.
- Order of Approval: The Consul General or the Commissioner of Immigration signs the formal Order of Approval granting the petition.
- Taking the Oath of Allegiance: You formally take and sign the Sworn Oath of Allegiance to the Republic of the Philippines before a commissioned consular or immigration officer.
- Issuance of Identification Certificate: The Bureau of Immigration issues your official Identification Certificate (IC), which serves as permanent, prima facie evidence of your restored Philippine citizenship.
Philippine Tax Identification Number (TIN) via BIR Form 1904
Many dual citizens who have lived abroad for decades assume they cannot purchase property because they do not have an active Philippine Tax Identification Number. Under BIR Revenue Regulations, any individual acquiring real property in the Philippines, whether resident or non-resident, must secure a TIN under Executive Order No. 98. This is accomplished by submitting BIR Form 1904 (Application for Registration for One-Time Taxpayer and Persons Registering Under E.O. 98) along with a copy of the dual citizenship Identification Certificate and foreign or Philippine passport to the Revenue District Office (RDO) holding jurisdiction over the property.
4. Step-by-Step Acquisition Workflow for Overseas Dual Citizens
Executing a real property acquisition while residing overseas involves multiple legal and administrative stages. To ensure complete title protection and prevent costly procedural mistakes, dual citizens should adhere to this sequential 5-stage conveyancing pipeline:
| Stage | Core Operational Tasks | Responsible Entity | Estimated Timeline |
|---|---|---|---|
| Stage 1: Due Diligence & Title Verification | Secure Certified True Copy of TCT from Registry of Deeds; verify encumbrances; conduct cadastral boundary survey; check Tax Declaration and real property tax payments; CENRO classification check | Licensed Real Estate Broker / Appraiser & Geodetic Engineer | 5 to 10 Business Days |
| Stage 2: Remote SPA & Contract Preparation | Draft parcel-specific Special Power of Attorney; execute before local notary abroad; secure Hague Apostille certificate; draft bilateral Deed of Absolute Sale | Dual Citizen Principal, Overseas Notary, Apostille Authority, Legal Counsel | 10 to 20 Business Days |
| Stage 3: Notarization & Payment Settlement | Attorney-in-fact signs Deed of Absolute Sale in the Philippines; notarization before Philippine notary public; release of purchase funds via escrow or manager check | Attorney-in-Fact, Property Seller, Notary Public | 1 to 2 Business Days |
| Stage 4: BIR ONETT eCAR Processing | Submit documentary docket to BIR RDO; calculate Capital Gains Tax (6%) and DST (1.5%); pay taxes at Authorized Agent Bank; obtain electronic Certificate Authorizing Registration | Attorney-in-Fact / Broker & Bureau of Internal Revenue | 15 to 30 Business Days |
| Stage 5: LGU Transfer Tax & RD Titling | Pay local transfer tax (0.50% to 0.75%) at Municipal/Provincial Treasurer; submit eCAR, tax clearance, and owner duplicate title to Registry of Deeds; transfer Tax Declaration | Attorney-in-Fact, Municipal Treasurer, Registry of Deeds, Municipal Assessor | 10 to 20 Business Days |
Stage 1: Rigorous Pre-Purchase Due Diligence
Before transferring any earnest money or signing a binding purchase agreement, the dual citizen or their appointed representative must verify the seller’s title directly at the source. This involves four mandatory investigative steps:
- LRA PhilRIS Title Verification: Never rely on a photocopy of a title provided by the seller or an unverified agent. Request an official Certified True Copy (CTC) directly from the Registry of Deeds where the property is registered, or via the Land Registration Authority (LRA) PhilRIS online portal. Check the back of the title (the Memorandum of Encumbrances) for adverse claims, notices of lis pendens, mortgage liens, or Section 4 Rule 74 annotations. For an exhaustive walkthrough of this procedure, review our guide on how to verify a land title in the Philippines.
- Assessor Office and Tax Verification: Visit the Municipal Assessor Office to confirm that the property’s Tax Declaration matches the technical description on the Torrens title. Verify with the Municipal Treasurer that all Real Property Taxes (amilyar) are paid up to date, securing an official Tax Clearance Certificate. Understand the legal boundaries between administrative records and Torrens registration by reading our guide on tax declaration vs land title in the Philippines.
- On-Site Boundary Relocation Survey: Engage a licensed geodetic engineer to locate the physical concrete boundary monuments (mojones) on the parcel. Boundary encroachment, overlapping titles, and unregistered rights-of-way represent the most frequent sources of provincial land litigation. Review our comprehensive manual on real estate due diligence in the Philippines before advancing funds.
- CENRO Land Classification Verification: For provincial parcels located in coastal, upland, or unclassified rural areas, verify with the local Community Environment and Natural Resources Office (CENRO) under the Department of Environment and Natural Resources (DENR) that the land is formally classified as Alienable and Disposable (A&D). Titled land that overlaps with timberland, mineral reserves, or protected national parks is void ab initio under the Regalian Doctrine.
Stage 2: Remote Special Power of Attorney under the Hague Apostille Convention
Most dual citizens cannot afford to spend months in the Philippines overseeing the titling process. Under Article 1878 of the Civil Code, any act of strict dominion, such as acquiring or conveying real property, requires a Special Power of Attorney (SPA). Article 1874 strictly dictates that any real estate conveyance conducted through an agent without written authority is void ab initio.
Since May 14, 2019, the Philippines has been a party to the Hague Apostille Convention. This means dual citizens residing in Apostille-contracting countries (including the United States, Canada, Australia, Japan, the United Kingdom, and European Union member states) no longer need to travel to a Philippine Embassy or Consulate for authentication. The procedure is streamlined:
- Draft a Property-Specific SPA: The SPA must explicitly identify the exact parcel by its Transfer Certificate of Title number, lot number, block number, surveyed area, and registered location. It must grant express authority to sign the Deed of Absolute Sale, represent the principal before the BIR and Registry of Deeds, apply for a TIN, and receive the new TCT. For a complete analysis of required legal clauses, examine our detailed brief on Special Power of Attorney for OFW property transfer.
- Local Notarization Abroad: The dual citizen signs the SPA before a local notary public in their city of residence abroad.
- Apostille Certification: The notarized SPA is submitted to the designated state or national Apostille authority (such as the Secretary of State in the US or the Department of Foreign Affairs and Trade in Australia). Once affixed with the official Apostille certificate, the document is fully valid and legally enforceable in the Philippines without red ribbons.
- Non-Apostille Countries: Dual citizens residing in non-Apostille countries (such as the United Arab Emirates, Saudi Arabia, or Qatar) must still undergo traditional consular legalization at the nearest Philippine Embassy or Consulate General.
Stage 3: Execution of the Deed of Absolute Sale
With the apostilled SPA in hand, the appointed attorney-in-fact represents the dual citizen during the formal execution of the Deed of Absolute Sale in the Philippines. The deed must strictly adhere to the 2004 Rules on Notarial Practice. Cedulas (Community Tax Certificates) are legally inadmissible as competent evidence of identity; the notary public must record government-issued photo identifications containing the photograph and signature of both parties.
Furthermore, if the seller is married, their spouse must execute written spousal consent on the deed pursuant to Article 96 of the Family Code (for Absolute Community of Property) or Article 124 (for Conjugal Partnership of Gains). Conveyances executed without mandatory spousal consent are void ab initio. Review our complete checklist of requirements in deed of absolute sale requirements in the Philippines.
Stage 4: BIR ONETT Tax Clearance and eCAR Issuance
Once the Deed of Absolute Sale is notarized, a strict statutory clock begins. Within 30 days from notarization, the Capital Gains Tax (CGT) return must be filed and paid. The Documentary Stamp Tax (DST) return must be filed and paid on or before the 5th day of the month following the date of the deed’s notarization.
The transaction docket is submitted to the BIR One-Time Transaction (ONETT) unit at the Revenue District Office holding jurisdiction over the land (for example, BIR RDO No. 12 in San Fernando, La Union, covering portions of Northern Luzon, or RDO No. 1 in Ilocos Norte). The BIR examines the deed, original title, certified tax declarations, and dual citizenship documents, verifies tax payments, and issues the official electronic Certificate Authorizing Registration (eCAR). Without an authentic eCAR with an active barcode, the Registry of Deeds is legally prohibited from transferring title under Section 58 of the National Internal Revenue Code. For an in-depth breakdown of this process, see our master guide on BIR eCAR requirements and processing.
Stage 5: Local Transfer Tax and Registry of Deeds Inscription
Upon receiving the eCAR, the attorney-in-fact proceeds to the Provincial or Municipal Treasurer Office to pay the Local Transfer Tax (typically 0.50% in provinces or 0.75% in cities) under Section 135 of the Local Government Code of 1991 (Republic Act No. 7160). The Treasurer issues the Official Tax Clearance and Transfer Tax Receipt.
Finally, the complete docket (original Owner Duplicate Title, notarized Deed of Absolute Sale, apostilled SPA, BIR eCAR, Tax Clearance, and Local Transfer Tax Receipt) is submitted to the Registry of Deeds. The RD examiner verifies the entry, cancels the seller’s title, and inscribes a brand-new Transfer Certificate of Title (TCT) issued in the dual citizen’s name. The final step is presenting the new TCT to the Municipal Assessor Office to issue a new Tax Declaration in the buyer’s name. Understand the complete fee schedule by reviewing our detailed breakdown of transfer of title costs in the Philippines.
5. Worked Financial Model: Taxes and Closing Expenses in Ilocos Sur
One of the primary concerns for dual citizens purchasing property is understanding the complete financial outlay beyond the agreed purchase price. In Philippine real estate transactions, statutory taxes and closing expenses are distributed between the seller and the buyer based on legal defaults or contractual agreements.
Below is a realistic, worked financial arithmetic model for a dual citizen purchasing a 3,000,000 PHP titled residential parcel (1,200 square meters) in provincial Ilocos Sur, assuming the selling price equals the zonal value and assessor fair market value:
| Tax or Transaction Fee | Statutory Basis / Rate | Customary Responsible Party | Calculated Amount (PHP) | Filing & Payment Deadline |
|---|---|---|---|---|
| Capital Gains Tax (CGT) | 6.0% of Gross Selling Price or Zonal Value (whichever is higher) under NIRC Section 24(D) | Seller (Unless contractually shifted to buyer) | 180,000.00 | Within 30 days from the date of notarization (BIR Form 1706) |
| Documentary Stamp Tax (DST) | 1.5% of Gross Selling Price or Zonal Value (whichever is higher) under NIRC Section 196 | Buyer (By market custom) | 45,000.00 | On or before the 5th day of the month following notarization (BIR Form 2000-OT) |
| Local Transfer Tax | 0.50% of Total Consideration or Fair Market Value in Provinces (RA 7160 Section 135) | Buyer | 15,000.00 | Within 60 days from the date of notarization at the Provincial/Municipal Treasurer |
| LRA Graduated Registration Fee | Graduated fee schedule under LRA Circular No. 11-2002 based on consideration | Buyer | 14,846.00 | Upon formal docket submission to the Registry of Deeds for title transfer |
| IT and PhilRIS Verification Fees | LRA computerized transaction fees and certification charges | Buyer | 1,100.00 | Simultaneous with LRA Registration Fee payment |
| Notarial Legal Fee | Standard 1.0% to 1.5% of transaction consideration before commissioned notary public | Buyer (or shared by agreement) | 30,000.00 | Paid upon formal execution and acknowledgment of Deed of Absolute Sale |
| Assessor Tax Declaration Transfer Fee | Municipal ordinance inspection and administrative filing fee | Buyer | 500.00 | Paid upon filing new Tax Declaration at the Municipal Assessor Office |
| Total Statutory Taxes & Fees | Combined Government Levies & Titling Costs | Seller & Buyer Combined | 286,446.00 | Complete Conveyancing Docket Settlement |
Note on Buyer Outlay: In standard transactions where the seller pays the 6% Capital Gains Tax and the buyer covers documentary stamps, local transfer tax, registration fees, and notarial charges, the buyer’s net closing costs amount to approximately 106,446.00 PHP (or about 3.55% of the total purchase price). Dual citizens should verify contract terms carefully; in “net to seller” arrangements, the buyer assumes all taxes, increasing their closing budget to 286,446.00 PHP (approximately 9.55% above the contract price).
6. Common Pitfalls and Legal Traps for Dual Citizens
Overseas buyers face unique legal vulnerabilities when acquiring provincial real estate in the Philippines. Drawing from our frontline practice at LandMaster Realty, here are the four most frequent and dangerous pitfalls dual citizens must avoid:
Pitfall 1: Buying Land with a Tax Declaration Only
Many attractive provincial parcels in Northern Luzon are marketed at low prices because they are covered solely by a Tax Declaration rather than a Torrens Transfer Certificate of Title. Unscrupulous sellers or relatives often reassure overseas buyers that “tax declarations prove ownership and can easily be titled later”.
This is a dangerous legal trap. The Supreme Court has repeatedly ruled (Cequena v. Bolante, G.R. No. 137944) that a Tax Declaration is merely evidence of an individual’s claim to possession for taxation purposes; it does not confer legal ownership, nor is it conclusive proof of title. Converting untitled tax declaration land into a registered Torrens title requires complex judicial confirmation of imperfect title under Republic Act No. 11573 or an administrative free patent under Republic Act No. 10023, requiring decades of continuous, open, and exclusive possession. If an adverse claimant emerges with an earlier tax declaration or an overlapping registered patent, the buyer can lose both the land and their entire financial investment.
Pitfall 2: Titling Land in the Name of a Non-Filipino Foreign Spouse
Some dual citizens, unfamiliar with constitutional nuances, attempt to include their foreign spouse as a named co-owner on the Deed of Absolute Sale. As noted, the Registry of Deeds will immediately reject the conveyance. More critically, entering into simulated contracts, trusts, or corporate arrangements designed to circumvent the constitutional ban on foreign land ownership violates the Anti-Dummy Law (Commonwealth Act No. 108). Under Section 2 of CA 108, both the foreign national and the Filipino citizen facilitating the transaction face criminal liability, fines, and potential forfeiture of the property to the State.
Pitfall 3: Unregistered Road Right of Way Easements
Interior agricultural and residential parcels in provincial areas often lack direct access to a public highway. Buyers frequently rely on verbal promises from the seller or neighboring relatives stating that “the family will always allow you to pass through their lot”.
Verbal rights of way are legally precarious and collapse when neighboring lots are sold or inherited by subsequent generations. Under Articles 649 and 650 of the Civil Code, an owner of an estate surrounded by other estates without adequate outlet to a public highway can demand a right of way, but this requires establishing the absence of self-isolation, paying proper indemnity, selecting the point least prejudicial to the servient estate, and navigating extensive court litigation if the neighbor refuses. Dual citizens must ensure that a formal, written, and notarized Deed of Easement of Right of Way is executed and registered as an official encumbrance on the servient estate’s title prior to closing.
Pitfall 4: Relying on Defective or Forged Special Powers of Attorney
When purchasing property from sellers who are themselves residing abroad or dealing through local relatives, dual citizens must verify the seller’s power of attorney with extreme caution. Common fraudulent practices include:
- Utilizing an SPA executed by a principal who has already passed away. Under Article 1919 of the Civil Code, agency is automatically extinguished upon the death of the principal. Any deed executed by an agent using an SPA after the principal’s demise is void ab initio.
- Presenting an SPA that lacks an official Hague Apostille or consular seal from the Philippine Embassy.
- Using a General Power of Attorney that lacks the express, parcel-specific authority required under Civil Code Article 1878 to sell real estate.
To safeguard your investment against sophisticated conveyancing fraud, review our practitioner guide on common land buying scams in the Philippines and how to avoid them.
7. Frequently Asked Questions (FAQ)
Do dual citizens have to pay higher property taxes than resident Filipinos?
No. Dual citizens are subject to the exact same statutory tax rates as resident Filipino citizens regarding real estate ownership and conveyancing. The Real Property Tax (amilyar) assessed by the Local Government Unit, the 6% Capital Gains Tax upon sale, and the 1.5% Documentary Stamp Tax apply equally regardless of where the dual citizen resides.
Can the foreign-born children of dual citizens own land in the Philippines?
If the child was born while at least one parent was still a Filipino citizen, the child is a natural-born Filipino under the principle of jus sanguinis (citizenship by blood) pursuant to Article IV, Section 1 of the 1987 Constitution. In this case, the child can apply for recognition as a dual citizen under RA 9225 and own land without area limits. However, if the child was born after both parents had already acquired foreign citizenship and before they reacquired Philippine nationality under RA 9225, the child is legally a foreign national and cannot hold freehold title to Philippine land except through hereditary succession.
Can dual citizens buy agricultural land under CARP?
Yes. Dual citizens can purchase agricultural land, but like all Filipino citizens, they are strictly subject to the 5-hectare landholding ceiling mandated by the Comprehensive Agrarian Reform Program (CARP) under Republic Act No. 6657. Any agricultural land transfer requires obtaining a DAR Clearance from the Department of Agrarian Reform confirming that the buyer’s aggregate agricultural landholdings do not exceed 5 hectares.
Can a dual citizen purchase property before taking the Oath of Allegiance?
No. Freehold property rights are restored only upon the formal taking of the Oath of Allegiance and the issuance of the Identification Certificate by the Bureau of Immigration or Philippine Foreign Service Post. If you purchase land while you are still purely a foreign national, your acquisition is governed by the restrictive 1,000 square meter limits of Batas Pambansa Blg. 185.
Does a dual citizen need to live in the Philippines to maintain land ownership?
No. There is no legal residency requirement for dual citizens to maintain freehold land ownership in the Philippines. You can reside permanently abroad while owning titled land in the country, provided that Real Property Taxes are paid annually to the local municipal treasurer.
What happens if a dual citizen loses their original Identification Certificate?
You can request a certified true copy or a replacement Identification Certificate from the Bureau of Immigration Main Office in Intramuros, Manila, or from the specific Philippine Embassy or Consulate where your dual citizenship petition was originally processed. The Registry of Deeds requires an authenticated copy to proceed with title registration.
Secure Professional Land Acquisition Support in Northern Luzon
Whether you are an overseas dual citizen purchasing residential property in Vigan City, prime beachfront land in Ilocos Sur, or agricultural acreage in Northern Luzon, LandMaster Realty provides licensed appraisal, independent title verification, and complete end-to-end conveyancing.